Some prices may slip, mostly condos, but nothing in the data points to a broad drop or a 2008-style crash. Houses and townhouses are forecast flat to slightly up for 2026, and what buyers have gained is more choice and more room to negotiate.
Updated October 6, 2026Freddie Mac, Fairfax County, Census, CFPB, FHFA, Zillow and the three local REALTOR associationsAbout a 9-minute read
No. Nothing in the data points to a 2008-style crash in Northern Virginia. In 2008, risky loans and a building boom led to waves of forced sales. Today 96.9% of Virginia mortgages are fixed rate, only 0.2% (Fairfax) to 0.7% (Prince William) of county mortgages were 90 or more days late in September 2025, the latest county data, and the counties build a fraction of what they did in 2004. Price forecasts for 2026 run from −0.2% (Fairfax condos) to +4.2% (Loudoun single-family homes). The soft spot is condos.
Four numbers that answer the question
Each one dated and sourced below
0.2%of Fairfax County mortgages were 90 or more days late in September 2025, down from 3.2% at the October 2009 peak.
53.5%of Virginia mortgages carried a rate under 4% in the first quarter of 2026. Few owners will trade that for a new loan at 7.28% (week of October 1, 2026).
86%fewer single-family homes permitted in Prince William: 5,307 in 2004, 726 in 2025.
2.08months of supply in the Fairfax, Arlington and Alexandria area in August 2026 (NVAR), less than half the national figure of 4.9 months.
2019 to 2026
Rates more than doubled. Prices kept rising.
If high rates alone could crash Northern Virginia, it would have happened in 2022. Fairfax County's average sale price rose every single year from 2019 to 2025, 46.9% in all. Every county's median, year by year: home prices since 2020, county by county.
Mortgage rates and Fairfax County prices, 2019 to 2026
30-year mortgage rate, yearly average1Fairfax County average sale price, all home types2
3.94%$602K+3.9%2019
3.11%$652K+8.4%2020
2.96%$709K+8.7%2021
5.34%$762K+7.4%2022
6.81%$790K+3.8%2023
6.72%$858K+8.6%2024
6.60%$884K+3.0%2025
6.43%$899KJuly only2026so far
2.65% The lowest 30-year rate on record, week of January 7, 2021.
7.28% The rate in the week of October 1, 2026, the latest at the time of writing.
The percent under each price is its change from the year before. 2026 rate: average of the weeks from January 8 to October 1, 2026. 2026 price: July 2026 alone, the latest month Fairfax County has published. Fairfax County publishes a yearly average for every year; a yearly median is not public for every year, so this chart uses the average throughout.
2019 to 2021
Cheap money
2.96%
Rates fell to the lowest on record, averaging 2.96% in 2021. Buyers rushed in, and Fairfax County's average sale price rose 8.4% in 2020 and 8.7% in 2021.
2022
Rates double
3.22% to 7.08%
The weekly 30-year rate went from 3.22% to 7.08% (the weeks of January 6 and November 10, 2022; Freddie Mac), more than doubling within one year, the fastest jump in four decades of data. Fairfax County's average sale price still rose 7.4%.
2023 to 2025
High rates, prices still up
+3.0% to +8.6%
The yearly average rate stayed between 6.6% and 6.8%. Fairfax County's average sale price still rose every year: 3.8% in 2023, 8.6% in 2024 and 3.0% in 2025.
2026
Cooling, not crashing
+1.7%
Fairfax County's average sale price in July 2026 was 1.7% above its 2025 average. Listings are up and sales are down, the pattern of a cooling market.
Before you trust that video
Northern Virginia is not one market, and it is not Florida.
Most "the crash is coming" videos on YouTube, TikTok and Instagram are about Florida, Texas or the country as a whole. You cannot copy those numbers onto Northern Virginia. Even here, some parts of the market are rising, some are flat and one is soft.
August 2026 figures cover all home types unless a row says otherwise. Forecasts are for the full year 2026.
From my own MLS pull
42,298 closed sales, side by side
I pulled every house, townhouse and condo sale in Fairfax, Loudoun, Prince William and Arlington counties and the Cities of Alexandria, Fairfax, Falls Church, Manassas and Manassas Park, for January 1 to October 2 in 2025 and again in 2026. Same nine months, same places, so the comparison is fair. The median sale price is shown with its change from the same period in 2025.
Houses
Detached, 3+ bedrooms, 2+ full baths · median sale price
$960,000
+1.9% vs $942,000 in 2025
Median days to sell
7 → 7
Share sold above the original asking price
41% → 43%
Price per sq ft above ground
$413 → $422
Months of supply
1.8
9,813 sales in 2026, 9,650 in 2025
Townhouses
You own the townhouse and its land (fee simple), not a condo · median sale price
$650,000
+0.8% vs $645,000 in 2025
Median days to sell
7 → 8
Share sold above the original asking price
44% → 40%
Price per sq ft above ground
$372 → $369
Months of supply
1.9
5,764 sales in 2026, 5,475 in 2025
Condo townhouses
Townhouses owned as condominiums · median sale price
$510,000
−1.4% vs $517,000 in 2025
Median days to sell
11 → 17
Share sold above the original asking price
32% → 26%
Price per sq ft above ground
$328 → $322
Months of supply
2.7
1,497 sales in 2026, 1,549 in 2025
Condos
Apartment-style units · median sale price
$378,750
+1.0% vs $375,000 in 2025
Median days to sell
15 → 22
Share sold above the original asking price
24% → 18%
Price per sq ft above ground
$362 → $353
Months of supply
3.5
3,762 sales in 2026, 3,807 in 2025
Median sale price, January 1 to October 2, 2026, and change from the same period in 2025
Place
Houses
Townhouses
Condos
Fairfax County
+1.5%$1,005,000
−0.3%$650,000
−1.5%$354,900
Loudoun
+2.1%$1,095,000
+0.7%$700,000
−6.8%$400,000
Prince William
+2.8%$740,000
+4.0%$525,000
+38.8%*$447,500
Arlington
+0.0%$1,400,500
−2.8%$1,037,500
+4.2%$433,000
City of Alexandria
+8.0%$1,350,000
+2.7%$915,000
+1.4%$365,000
Source: Bright MLS, closed sales January 1 to October 2, 2025 (20,936) and January 1 to October 2, 2026 (21,362); 5,124 homes for sale on October 6, 2026. Houses are detached homes with 3 or more bedrooms and 2 or more full baths. The four home-type cards add up to 20,481 sales in 2025 and 20,836 in 2026; the totals also count smaller detached homes (under 3 bedrooms or 2 full baths) and a few records left out as likely errors. Days to sell is the median cumulative days on market. Price per square foot uses finished space above ground, so it reads high for homes with finished basements. Months of supply is the homes for sale on October 6 divided by the average month of closed sales in 2026. Likely data-entry errors in the MLS records were left out: sales under $75,000 or over $15 million, and square footage or sale-to-list figures that cannot be right. The Cities of Fairfax, Falls Church, Manassas and Manassas Park are in the totals but have too few sales of each type for their own row. *Prince William condos: 113 of the 282 sold in 2026 were in buildings finished in 2024 or later, which lifted the median. It is not a like-for-like gain.
The pattern is clear. Houses and townhouses still sell in about a week, and four in ten go above the original price. Condos have slowed: they take three weeks, fewer than one in five sells above the original price, and they have about twice the months of supply of houses (3.5 against 1.8). That is a soft corner of the market, not a crash.
The recipe
A crash needs three things. In 2008 Northern Virginia had all three.
Prices only collapse when many owners must sell at the same time. That takes loans people cannot pay, more homes than buyers, and a wave of foreclosures. Here is each one, then and now.
Risky loans
The 2008 bust18.4%
of 2005 mortgages in Prince William County came from subprime lenders (lenders that made high-cost loans to borrowers with weak credit).5
Now96.9%
of Virginia mortgages today are fixed rate. The payment cannot reset.7
Too many new homes
The 2008 bust5,307
single-family homes permitted in Prince William County in 2004.3
Now726
single-family homes permitted there in 2025, 86% fewer.3
Forced sellers
The 2008 bust5.8%
of Prince William mortgages were 90+ days late at the peak, January 2010.6
Now0.7%
of Prince William mortgages were 90+ days late in September 2025.6
Honest history
It did happen here. Prince William lost 43%.
Anyone who says "Northern Virginia never crashes" is wrong. What matters is why it happened, and whether the same machine is running today.
How far prices fell, peak to bottom, 2006 to 20094
Drop in home valuesSubprime share of 2005 loans
Prince William CountyJul 2006 to Sep 2009−43.4%18.4%
Loudoun CountyApr 2006 to Sep 2009−34.5%9.5%
Fairfax CountyApr 2006 to Apr 2009−26.2%11.1%
Arlington CountyMar 2006 to Aug 2009−12.2%5.5%
The more subprime lending a county had, the further it fell (subprime share: Urban Institute5). Prince William got its peak price back in May 2021, Loudoun in October 2020, Fairfax in December 2017 and Arlington in October 2013. Those are prices in the dollars of each year, not adjusted for inflation.
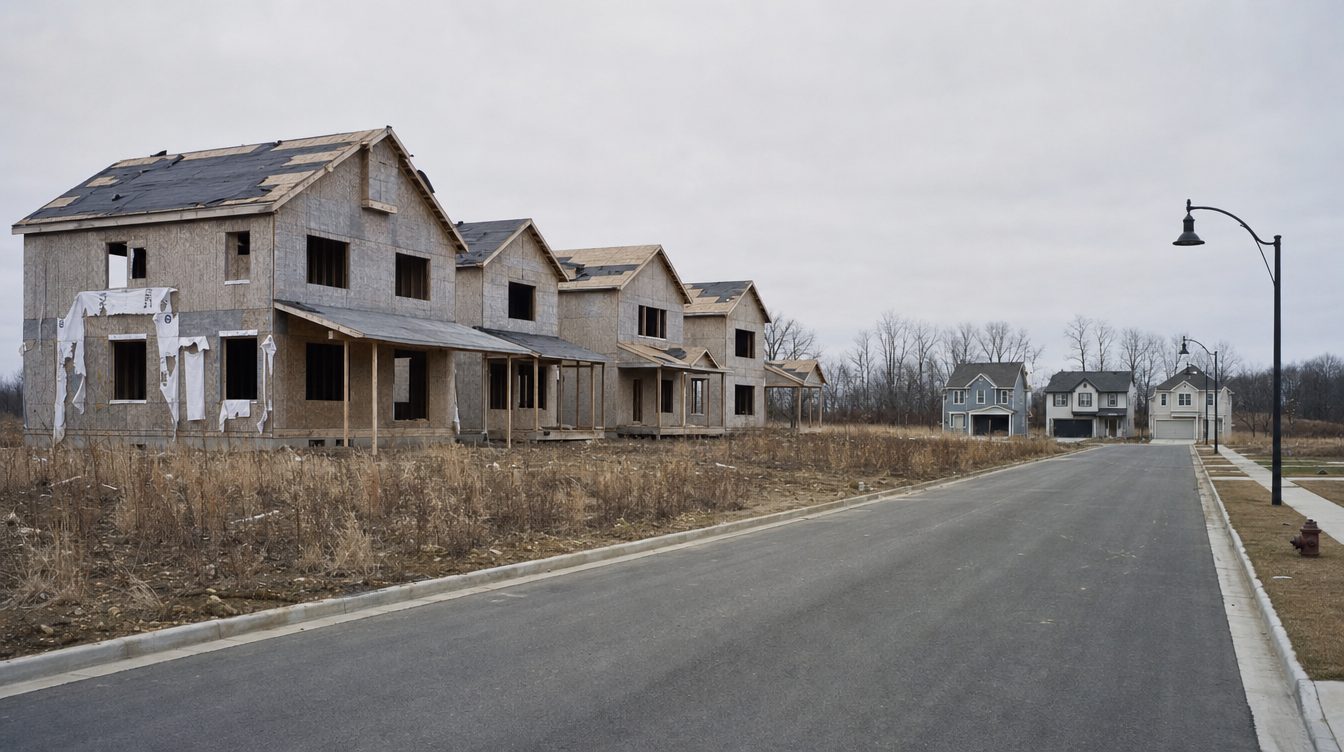
2008 left half-built subdivisions across the outer counties. Illustration
The outer counties fell hardest. One in five Prince William mortgages in 2005 came from a subprime lender, and Prince William and Loudoun were each permitting more than 5,000 new houses a year.
Arlington fell the least, 12.2%. It had the least subprime lending and permitted only 184 single-family homes in 2004. It could not overbuild.
Today those loans are gone. Since 2014, federal ability-to-repay rules make lenders check income and qualify buyers at the loan's full payment, so the no-documentation loans of 2005 have disappeared. Single-family building is down by more than 85% in both counties.
Same crash, different neighborhoods: 2006 to 2009 drop by zip code4
Dale City (22193)−51.4%
Woodbridge (22191)−50.9%
Dumfries (22026)−48.9%
Sterling (20164)−44.4%
Ashburn (20147)−34.1%
South Riding (20152)−33.3%
Centreville (20120)−31.3%
Vienna (22182)−20.1%
North Arlington (22207)−8.8%
A 43-point spread inside one region, from −51.4% in Dale City to −8.8% in North Arlington. "Northern Virginia" never moves as one market.
Florida and Texas
They overbuilt. We did not.
The price drops you see in the news are real, in the places that built the most: Austin, Florida's Gulf Coast, Phoenix, Denver and Dallas. Two numbers from one Census Bureau file show the difference.
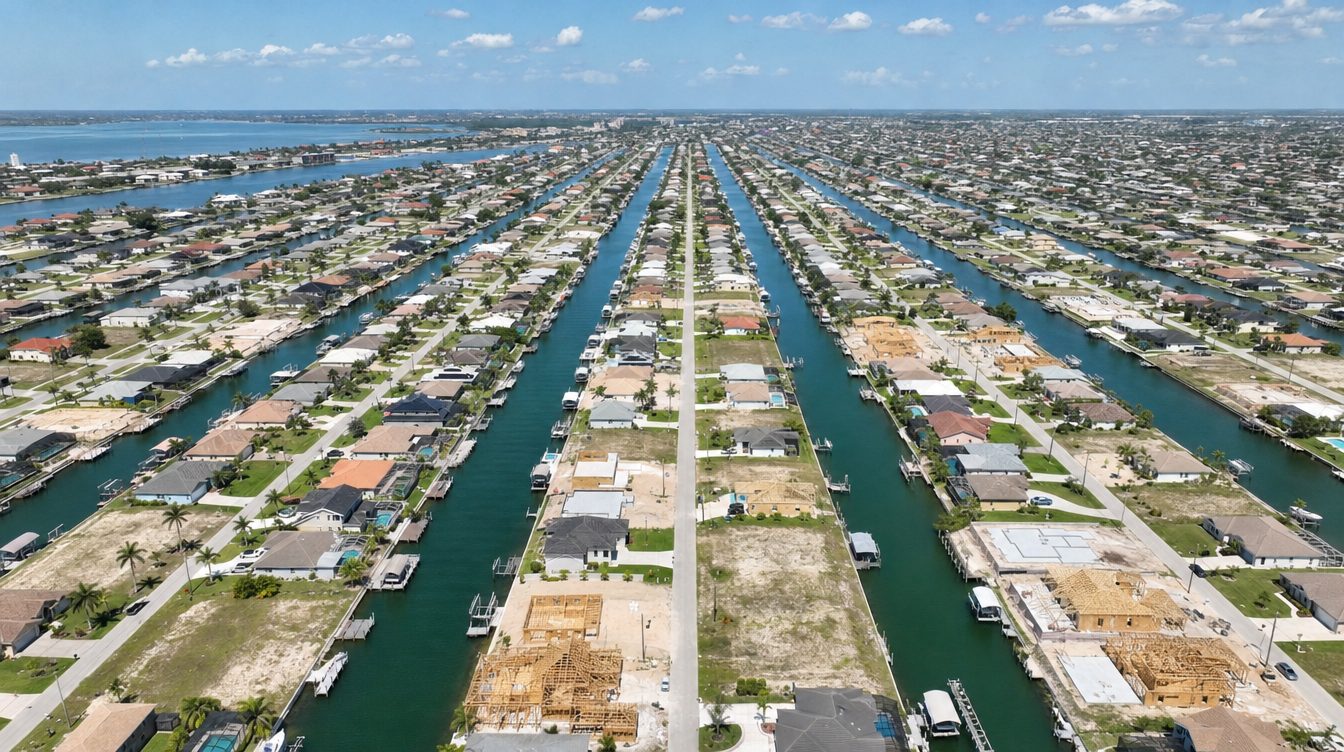
Cape Coral, Florida, where new houses kept going up faster than buyers arrived. Illustration
Cape Coral–Fort Myers, Florida9,962single-family homes permitted in 2025876,000 people
vs
The whole Washington metro10,168single-family homes permitted in 20256,465,724 people
A region one-seventh our size built almost as many houses. Per person, that is 7.2 times as much building.3
New homes permitted per 1,000 people, 2025, all home types3
Sarasota, FL18.61
Cape Coral, FL15.47
Austin, TX10.42
Houston, TX8.23
Dallas–Fort Worth, TX7.81
Washington metro2.78
This chart counts all home types, apartments included, so the gap is smaller than the 7.2 times for single-family homes above.
Home values against their 2022 peak, August 202614
Austin, TX−27.6%
Punta Gorda, FL−24.5%
Cape Coral–Fort Myers, FL−19.3%
North Port–Sarasota, FL−16.9%
Phoenix, AZ−11.9%
Naples, FL−11.8%
San Antonio, TX−10.8%
Denver, CO−10.0%
Dallas–Fort Worth, TX−9.5%
Tampa, FL−8.5%
Washington metro+4.2%
The ten large metros furthest below their 2022 peak, on Zillow's home value index. The Washington metro is 4.2% above its 2022 peak.
Florida's Gulf Coast
Built fast, then insurance hit
Prices jumped in the pandemic, then a wave of new homes, rising insurance premiums and investors selling pushed values down. Cape Coral, Punta Gorda and Sarasota are 17% (Sarasota) to 25% (Punta Gorda) below their 2022 peak.14,17
Texas
More sellers than buyers
New-home supply outran demand. Of the 50 largest metros, only five had lower prices in August 2026 than a year earlier on Redfin's index, and four of those five were in Texas.15
Washington metro
Softer, not crashing
Values are 4.2% above the 2022 peak. Listings are up 16.2% from a year ago and one in five has had a price cut, which means more room to negotiate, not a collapse.14,16
Why owners stay put
More than half of Virginia mortgages are under 4%.
An owner paying 3% has every reason to keep the house and the loan. That keeps the number of homes for sale low, and a short supply holds prices up.
A low fixed rate is the best thing many owners have. Few will give it up. Illustration
Share of Virginia mortgages by interest rate, first quarter of 20267
Under 3%22.9%
Under 4%53.5%
Under 5%68.9%
Under 6%79.9%
Average rate on existing Virginia mortgages, first quarter of 2026 4.3%Rate on a new loan, week of October 1, 2026 7.28%
Each row includes the rows above it: 53.5% of Virginia mortgages carry a rate under 4%, and 79.9% are under 6%.
No reset wave is coming. In 2008, adjustable loans jumped to higher payments and owners could not pay. Today 96.9% of Virginia mortgages are fixed: the payment stays the same for the life of the loan.7
The distress check
Nobody is being forced to sell.
Foreclosures are how a crash spreads: the bank sells at any price, and that sale becomes the comparable for the street. In Fairfax and Prince William, late payments are below their 2019 average; in Loudoun they are a little above it (0.3% against 0.22%), and all three are far below their 2009 and 2010 peaks.
The newest county figures are for September 2025, the latest the federal data covers by county.
Lived-in streets: owners are paying on time. Illustration
Underwater homes are rare. 2.9% of mortgaged Virginia homes owed at least 25% more than they were worth (what ATTOM calls seriously underwater) in the second quarter of 2026, against 3.2% nationally. It was 2.4% the quarter before, so it is edging up.13
Foreclosures stay below the national rate. In August 2026, 1 in every 5,006 Virginia homes had a foreclosure filing, against 1 in 3,569 nationally.13
Months of supply
If no one listed a new home, the shelves would be empty in about two to three months.
Months of supply is how long the homes for sale today would last at the current pace of sales. A low number means buyers compete for few homes; a high number means sellers compete for few buyers. Northern Virginia is at about two to three months, well under the national figure of 4.9 months (August 2026), and rising from a year ago in the Fairfax, Arlington and Alexandria area and in Prince William (flat in Loudoun), so buyers have more choice than they did.
Months of supply, August 2026, all home types
1.9months
Loudoun County
1.9 a year earlier. Dulles Area Association of REALTORS, August 2026.9
2.08months
Fairfax, Arlington and Alexandria area
about 1.8 a year earlier (up 14.7%). Northern Virginia Association of REALTORS, August 2026.8
2.8months
Prince William, Manassas and Manassas Park
1.8 a year earlier. Prince William Association of REALTORS, August 2026.10
4.9months
United States
for comparison. Northern Virginia Association of REALTORS (NVAR) national comparison, August 2026.8
0123456 months
Each association counts its own area, so the Loudoun figure from the Dulles Area Association (1.9) differs slightly from the Northern Virginia Association's count for Loudoun (2.09). All figures cover houses, townhouses and condos together.
What forecasters expect
The forecasts are flat to slightly up. A crash is a different scale.
2026 price forecasts by the Northern Virginia Association of REALTORS and George Mason University, June 202612
Zero
Loudoun, single-family+4.2%
Arlington, single-family+3.9%
Prince William, single-family+3.3%
Fairfax, single-family+1.5%
Fairfax, townhouses+1.5%
Alexandria, single-family+1.1%
Stafford, single-family−0.1%
Fairfax, condos−0.2%
For scale: Prince William, 2006 to 2009−43.4%
The forecasts sit in a thin sliver around zero. The bottom bar is what a real crash looked like here, drawn on the same scale.
What counts as a crash?
Each band is the drop from the peak price.
0% to −5%
Cooling2026
Prices flat or easing, more homes for sale, sales slower. Where 2026 is now.
−5% to −10%
Correction
A normal dip. Possible in condos or at the top of the market if rates climb further.
−10% to −20%
Deep correction
Arlington County in the last bust: down 12.2% from its March 2006 peak to August 2009. It is the only county or zip code in the 2006 to 2009 charts above that landed in this band.
−20% or worse
Crash
2008 in Prince William, Loudoun and Fairfax. It took subprime loans, thousands of new homes a year and a wave of foreclosures.
Latest values, August 2026: Zillow's home value index puts Fairfax at $760,599 (+0.8% from a year earlier), Loudoun at $795,391 (+1.4%) and Prince William at $581,036 (+1.1%).11
The honest part
What could still go wrong.
No crash does not mean no risk. These are the numbers to watch.
Condos
Condo listings in the Fairfax, Arlington and Alexandria area (the area the Northern Virginia Association of REALTORS, or NVAR, reports on) are up 44.8% from a year ago, and Fairfax condos are forecast at −0.2% for 2026. This is where prices can slip.8
Rates at 7.28%
The rate on a new loan was 7.28% in the week of October 1, 2026, up from 6.34% a year earlier. High rates slow sales and squeeze budgets.1
More homes for sale
Active listings in the Fairfax, Arlington and Alexandria area are up 18.5% and closed sales down 8.0% from August 2025, and across the Washington metro one listing in five has had a price cut. Good for buyers; sellers need sharp pricing.8,16
Older late-payment data
The county late-payment figures run through September 2025. Anything that changed after that is not yet in the federal data.6
Underwater homes edging up
Virginia's seriously underwater share rose from 2.4% to 2.9% in one quarter. Still below the nation, but moving the wrong way.13
Old prices, not real gains
Prince William's peak price came back in 2021, but in 2021 dollars. Getting the price back is not the same as making money after inflation.
Waiting for a 30% drop? The data does not support it. What has changed is choice: more homes for sale and more room to negotiate. Tell me your budget and the area, and I will show you what that means for you.
Some prices may slip, but the data does not point to a broad drop. The June 2026 forecast by the Northern Virginia Association of REALTORS and George Mason University has single-family prices rising in 2026 in Loudoun (+4.2%), Arlington (+3.9%), Prince William (+3.3%) and Fairfax (+1.5%). The soft spot is condos: Fairfax condos are forecast at −0.2%, and condo listings in the Fairfax, Arlington and Alexandria area were up 44.8% in August 2026 from a year earlier. What has changed is choice, with more homes for sale and more room to negotiate.
Will Northern Virginia home prices crash in 2026?
Nothing in the data points to a 2008-style crash. A crash needs risky loans, too many new homes and forced sellers. Today 96.9% of Virginia mortgages are fixed rate (FHFA, first quarter of 2026), only 0.2% (Fairfax) to 0.7% (Prince William) of mortgages in Fairfax, Loudoun and Prince William were 90 or more days late in September 2025 (CFPB), and Prince William permitted 726 single-family homes in 2025 against 5,307 in 2004 (US Census Bureau). Forecasters expect 2026 price changes from about −0.2% (Fairfax condos) to +4.2% (Loudoun single-family homes).
Did Northern Virginia home prices crash in 2008?
Yes. On the Zillow Home Value Index, Prince William County fell 43.4% from July 2006 to September 2009, Loudoun 34.5%, Fairfax 26.2% and Arlington 12.2%. The deepest drops were in the counties with the most subprime lending and the most new building.
Is the Northern Virginia market like Florida or Texas?
No. In 2025 Cape Coral–Fort Myers, with 876,000 people, permitted 9,962 single-family homes; the whole Washington metro, with 6.47 million, permitted 10,168 (US Census Bureau). Places that overbuilt are well below their 2022 peak values: Austin −27.6% and Cape Coral −19.3% in August 2026 (Zillow), while the Washington metro was 4.2% above its 2022 peak.
What is months of supply, and what is it in Northern Virginia?
Months of supply is how long the homes for sale would last if no new listings came and sales kept their current pace. In August 2026 it was 1.9 months in Loudoun (Dulles Area Association of REALTORS), 2.08 in the Fairfax, Arlington and Alexandria area (Northern Virginia Association of REALTORS) and 2.8 in Prince William (Prince William Association of REALTORS), against 4.9 for the United States. It is rising from a year ago in the Fairfax, Arlington and Alexandria area and in Prince William (flat in Loudoun), so buyers have more choice than they did.
Which part of the Northern Virginia market is weakest?
Condos. Condo listings in the Fairfax, Arlington and Alexandria area were up 44.8% in August 2026 from a year earlier, and the Northern Virginia Association of REALTORS (NVAR) and George Mason University forecast has Fairfax condos at −0.2% for 2026, while single-family homes are forecast to rise.
Should I wait for a crash to buy in Northern Virginia?
Waiting for a 20% to 30% drop is a bet against the data above. What has changed is choice: listings are up and homes take longer to sell than a year ago, which gives buyers more room to negotiate. The right timing depends on your rate, your budget and how long you will stay.
If mortgage rates drop, will home prices go up in Northern Virginia?
They did the last time. When the 30-year rate averaged 3.11% in 2020 and 2.96% in 2021, the lowest on record, Fairfax County’s average sale price rose 8.4% and then 8.7%.12 Lower rates let the same monthly payment borrow about 11% more for each point, so more buyers compete for the same homes. That is what happened, not a forecast. If you are weighing it, read should I wait for rates to drop? and what 1 point on the rate costs a month.
Your next step
Buying or selling in this market? Get the numbers for your street.
Send your situation and get real numbers back, in English or Arabic, not a pitch.